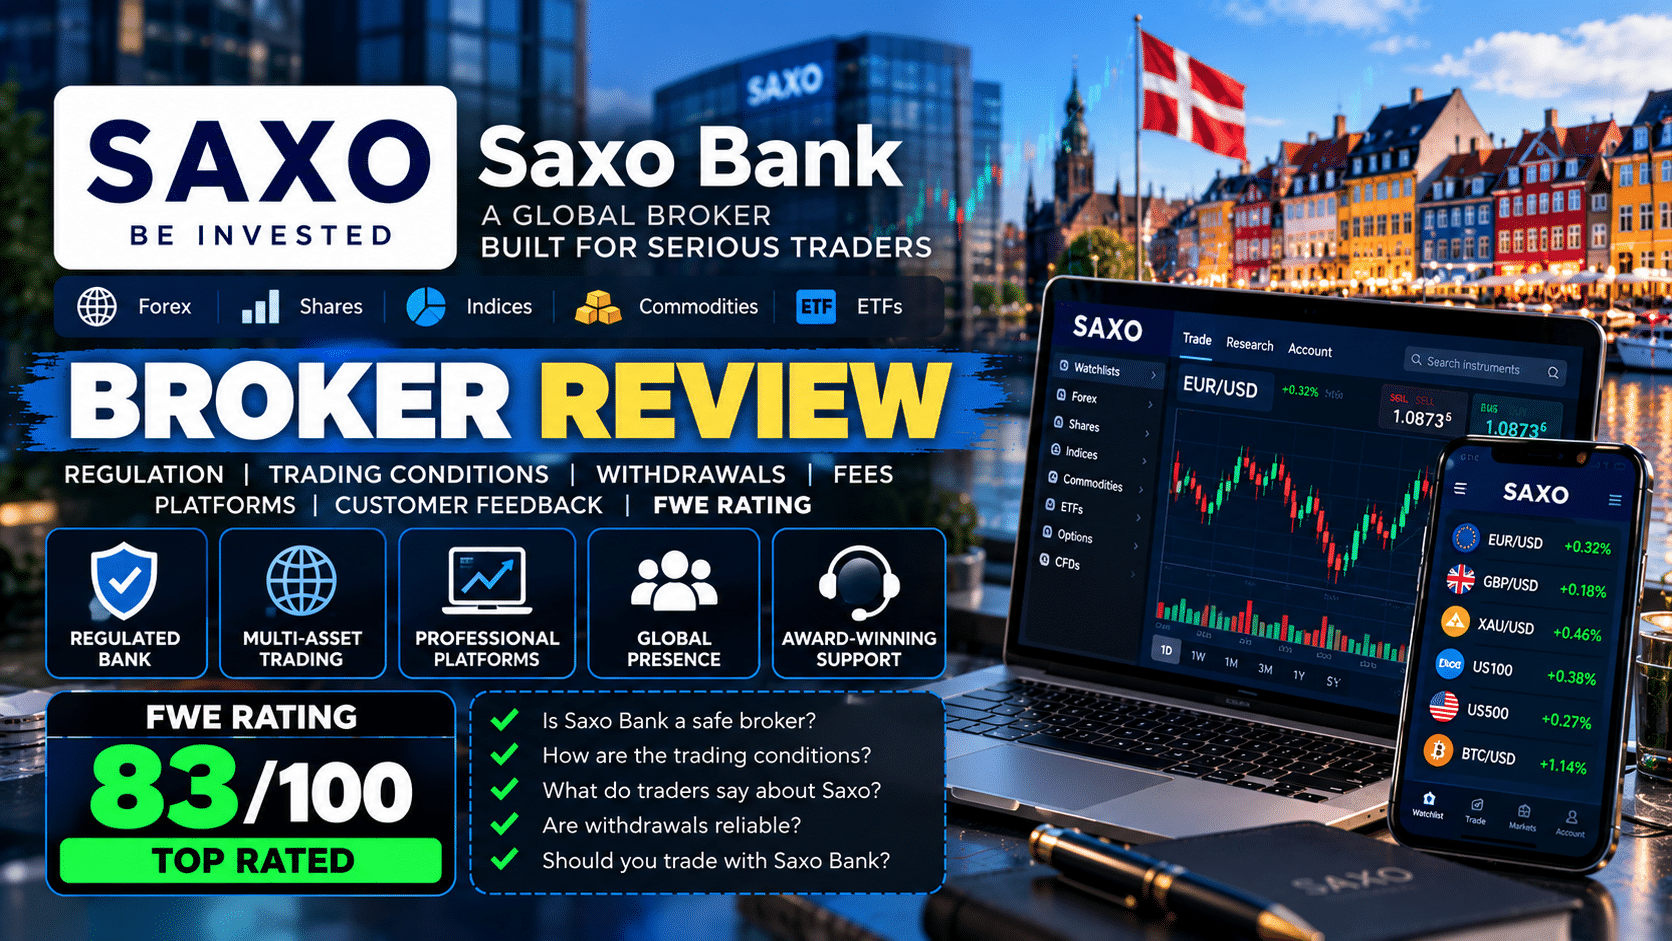
Saxo Bank review: A banking licence, professional platforms and decades of operating history make Saxo a notable name in global investing. Yet a serious anti-money-laundering penalty and later supervisory orders show why even an established institution deserves scrutiny. This independent Forex Wave Expert review weighs regulation, withdrawals, fees, customer experiences and the evidence behind each concern.
FWE editorial rating: 83/100 — Top Rated. This is an assessment of the company and its public record, not a guarantee of deposits, account access, trading outcomes or suitability.
Saxo Bank Review: Key Facts and Overview
| Legal name | Saxo Bank A/S |
|---|---|
| Founded | 1992 |
| Head office | Denmark |
| Business | Licensed bank and multi-asset investment / trading provider |
| Primary oversight | Danish Financial Supervisory Authority |
| Client assets (year-end 2025) | DKK 995 billion, company-reported |
| FWE rating | 83/100 — Top Rated |
What Is Saxo Bank?
Saxo began in 1992 and subsequently developed into a Danish-licensed bank with international investment and trading operations. It is not simply an offshore forex brand: its public reporting includes banking capital information and group financial statements. However, the precise service, legal entity and protections depend on where a customer lives and which products are involved.
The group reported more than 1.5 million clients and DKK 995 billion in client assets in its results for 2025. These are company-published figures rather than an independent guarantee of client outcomes. Sources: Saxo company results and Saxo investor reports.
Saxo Bank Regulation and Client Fund Safety
The Danish FSA is the principal supervisor of Saxo Bank A/S. Saxo also operates through different legal arrangements internationally. Banking supervision, capital rules and public risk reports support its institutional profile, but readers should not assume that every international account has identical deposit protection or investor compensation. The product and contracting entity determine which safeguards may apply.
For primary documentation, see Saxo investor reports and Saxo capital disclosures.
Saxo Bank AML Fine: What the Danish Regulator Found
Verified regulatory finding: On 23 January 2026, Denmark’s FSA announced that Saxo Bank had accepted an administrative fine of DKK 313 million for failures involving customer due diligence and ongoing monitoring. The authority described shortcomings involving certain customer relationships and white-label clients, principally in the period January 2021 to May 2023. It also noted Saxo’s cooperation and remedial measures. Source: AML enforcement.
This is a substantial compliance failure and must count against the regulation score. It does not by itself establish that Saxo stole customer funds, that a particular withdrawal was refused unlawfully, or that every client relationship was affected.
Regulatory Order on Saxo Fees and Interest Terms
Verified regulatory finding: In June 2026 the Danish FSA ordered Saxo to amend business terms that, in certain circumstances, permitted adverse changes to interest, fees or other remuneration without advance notice. The regulator considered the clauses inconsistent with applicable fair-business requirements. Source: Fee-terms order.
The issue matters to transparency because the clarity of contractual rights is part of customer protection. It is not evidence that every customer was charged an improper fee.
Product Governance and Complex-Investment Oversight
In July 2026 the Danish FSA published findings from a thematic inspection of Saxo’s product governance and appropriateness assessments. It identified weaknesses in management reporting and the ability to monitor sales outside the intended target market, and ordered improvements. Source: Product-governance order.
This matters especially when a provider offers complex instruments to retail customers. The order concerns governance and oversight; it should not be exaggerated into a claim that all Saxo products were mis-sold.
Saxo Bank Withdrawal Review: Processing and Access
Withdrawal complaints deserve attention even where a bank is strongly supervised. Public feedback about Saxo includes reported delays, requests for additional compliance documents, transfers taking longer than expected and difficulty receiving a clear explanation. These are individual customer allegations; FWE has not independently examined the underlying account files or established a general failure to return client funds.
Verification and anti-financial-crime controls can legitimately delay transactions. The quality of the process depends on whether document requests are clear, updates are timely and complaints can be escalated. Saxo receives 16/20 for Withdrawals & Fund Access, with a deduction for publicly reported friction.
For current customer accounts rather than verified rulings, consult Saxo customer feedback.
Saxo Bank Customer Complaints: What They Can and Cannot Show
Customer-review sites contain both praise and criticism. Some reviewers report helpful employees, functional platforms and efficient service. Others describe slow communication, confusing account restrictions or disappointing transfer experiences. Online comments are useful signals, but reviewers can omit facts, cases can be resolved privately and the overall rating changes over time.
FWE does not treat review-site scores as audited measures of reliability. Source for ongoing public feedback: Saxo customer feedback.
Saxo Trading Platforms and Market Coverage
Saxo is known for multi-asset investing and professional-style interfaces covering a broad range of instruments. That breadth is a strength for evaluating the business, but it also creates complexity. Access to forex, shares, bonds, exchange-traded products and derivatives varies by country and account type. Availability of an instrument does not make it appropriate for every investor.
Our Trading Conditions & Execution score is 13/15. The score recognises product depth and established infrastructure, while reserving points because fees, execution quality and customer experiences are not uniform across markets.
Saxo Fees, Spreads, Commissions and Currency Conversion
A Saxo Bank fees review should distinguish between dealing spreads, instrument commissions, financing costs, custody charges where applicable, currency conversion and transfer-related charges. No single universal “Saxo spread” represents all account types and jurisdictions. Fee schedules can change, so fixed pricing figures without a dated, entity-specific source can mislead.
The most useful primary references are Saxo’s regional fee schedule and Saxo legal documentation. The Danish regulator’s Fee-terms order is also relevant when evaluating contractual transparency.
Positive Saxo Reviews and Strengths
Saxo’s clearest strengths are its long history, banking status, public reporting, breadth of investment markets and developed technology. These are more durable evidence points than a handful of glowing testimonials. Its financial reporting and published capital disclosures also make parts of the group easier to evaluate than a broker with no accessible accounts.
Company disclosures: Saxo investor reports and Saxo capital disclosures.
Customer Support and Dispute Handling
A complaint-handling process matters most when something goes wrong. Saxo publishes legal and complaint-related documentation, which is positive. Public reviewers nevertheless describe uneven response times and frustration over compliance requests. Those claims should be distinguished from regulatory findings; they are not a verified count of unresolved cases.
FWE proposes 7/10 for Customer Support & Dispute Handling. The rating reflects documented channels and mixed reported experiences, rather than an independently measured resolution rate.
Saxo Bank Review Bangladesh: Availability and Local Protection
Readers searching for Saxo Bank review Bangladesh, Saxo Bank Bangladesh withdrawal or is Saxo available in Bangladesh should be careful not to confuse a Danish banking licence with permission to provide every product in Bangladesh. FWE has not verified Bangladesh-specific onboarding eligibility, local authorisation, local deposit routes or a representative sample of withdrawals from Bangladesh.
International brand recognition alone cannot establish the legal protections of a Bangladesh resident. This section is intended to clarify the jurisdiction question, not to imply that local access is confirmed.
Saxo Bank Pros and Cons
Positive Points
- Operating history dating to 1992
- Danish-licensed bank with supervisory oversight
- Published annual reports and capital disclosures
- Broad multi-asset market coverage
- Established trading and investment infrastructure
Main Concerns
- DKK 313 million AML fine accepted in 2026
- Regulatory order regarding fee and interest terms
- Product-governance supervisory findings
- Public complaints about transfers and support
- Costs and safeguards vary by entity and product
Saxo Bank FWE Rating: 83/100 — Top Rated
| FWE Rating Category | Score |
|---|---|
| Regulation & Fund Safety | 23/25 |
| Withdrawals & Fund Access | 16/20 |
| Reputation & Client Complaints | 11/15 |
| Trading Conditions & Execution | 13/15 |
| Transparency & Terms | 8/10 |
| Customer Support & Dispute Handling | 7/10 |
| Track Record | 5/5 |
| Total FWE Rating | 83/100 — Top Rated |
Why Saxo Receives an 83/100 FWE Rating
Category-by-category explanation
Regulation (23/25): Danish banking supervision and public capital reporting are substantial positives, offset by material regulatory enforcement. Withdrawals (16/20): Established processes but some reported verification and transfer friction. Reputation (11/15): Recognised brand with mixed public feedback and regulatory criticism. Trading (13/15): Broad markets and platforms, but pricing and suitability concerns remain. Transparency (8/10): Strong disclosures alongside an adverse fee-terms order. Support (7/10): Formal channels, but mixed customer experiences. Track Record (5/5): More than three decades of operating history.
The score is FWE’s comparative editorial opinion, not a regulator-issued safety rating or a statistical estimate of customer satisfaction.
Is Saxo Bank Safe or a Scam?
Saxo Bank is an established licensed Danish bank, not an anonymous trading website. That is a meaningful distinction, but “regulated” does not mean “risk-free.” The bank’s regulatory penalties and orders are genuine matters of public record, and complex products can produce substantial losses regardless of the provider’s corporate status. It would be inaccurate either to call Saxo a proven scam on this evidence or to claim its customers cannot face serious problems.
Related Forex Broker Reviews
For contrasting editorial assessments, explore the FWE Forex Broker Reviews directory, the IG Broker Review, CentFX Review, DB Investing Review and InstaForex Review.
FWE Final Assessment
Saxo has the scale, public reporting and institutional structure that justify a strong editorial assessment. Its multi-asset offering and long operating history stand out.
The 2026 AML penalty and subsequent supervisory orders cannot be overlooked. Alongside mixed customer feedback on transfers and support, they explain why FWE rates Saxo 83/100 — Top Rated, below IG’s existing 88/100 editorial rating. This conclusion is an evidence-weighted review, not an invitation to engage in leveraged trading.
Saxo Bank Review FAQ
What is Saxo Bank’s FWE rating?
Saxo receives a proposed FWE editorial rating of 83/100, in the Top Rated band.
Is Saxo Bank regulated?
Yes. Saxo Bank A/S is supervised by the Danish Financial Supervisory Authority. Other legal entities and protections vary by jurisdiction.
Did Saxo Bank receive an AML fine?
Yes. The Danish FSA announced a DKK 313 million administrative fine accepted in January 2026 for identified due-diligence and monitoring breaches.
Are there Saxo withdrawal complaints?
Public customer reviews contain reports of delays and document-verification difficulties, but those individual allegations are not independently verified by FWE.
Are Saxo trading fees low?
Costs depend on instrument, region, account and fee category; a universal low-fee claim would be misleading.
Is Saxo available in Bangladesh?
FWE has not independently verified local account eligibility or Bangladesh-specific authorisation.
Is Saxo Bank a scam?
It is an established licensed bank. This does not remove investment risks, operational disputes or the significance of its regulatory findings.
Why is Saxo rated below IG?
FWE’s proposed Saxo score accounts for material recent regulatory enforcement and reported service issues, while IG retains its previously assigned 88/100 editorial score.
Sources and Evidence
- AML enforcement
- Fee-terms order
- Product-governance order
- Saxo investor reports
- Saxo legal documentation
- Saxo capital disclosures
- Saxo customer feedback
- Saxo company results
Follow Forex Wave Expert
For educational market updates and new broker research, visit the Forex Wave Expert Telegram channel.
FWE Editorial Transparency
This independent review distinguishes company disclosures, regulator findings, public customer allegations and FWE editorial opinion. The 83/100 score is not a regulator score. No Saxo affiliate or offer link is included. Sources were checked in October 2026; the article title and slug deliberately contain no year.
Risk Warning
Forex, CFDs, derivatives and other leveraged products can cause rapid and substantial losses. This material is general educational research, not personal financial, investment or legal advice. Customer protections depend on product, entity and jurisdiction.